Financial Advice for Women: 4 Steps to Get Started
One of the most useful financial steps you can take is to list your monthly take-home pay, essential expenses, debts, savings, and irregular costs such as insurance premiums or car repairs; that gives you a starting point for decisions rather than a budget based on guesswork. If your income varies, build your plan around a conservative month and decide in advance where extra income will go, whether that is toward overdue bills, savings, or a specific goal.
Review the numbers regularly, especially after a job change, move, relationship change, or caregiving shift, because a plan that worked last year may not fit your life now. Our The Money Confidence Power-Up for Women Checklist is a digital download you can consider alongside this process if you prefer a checklist format.
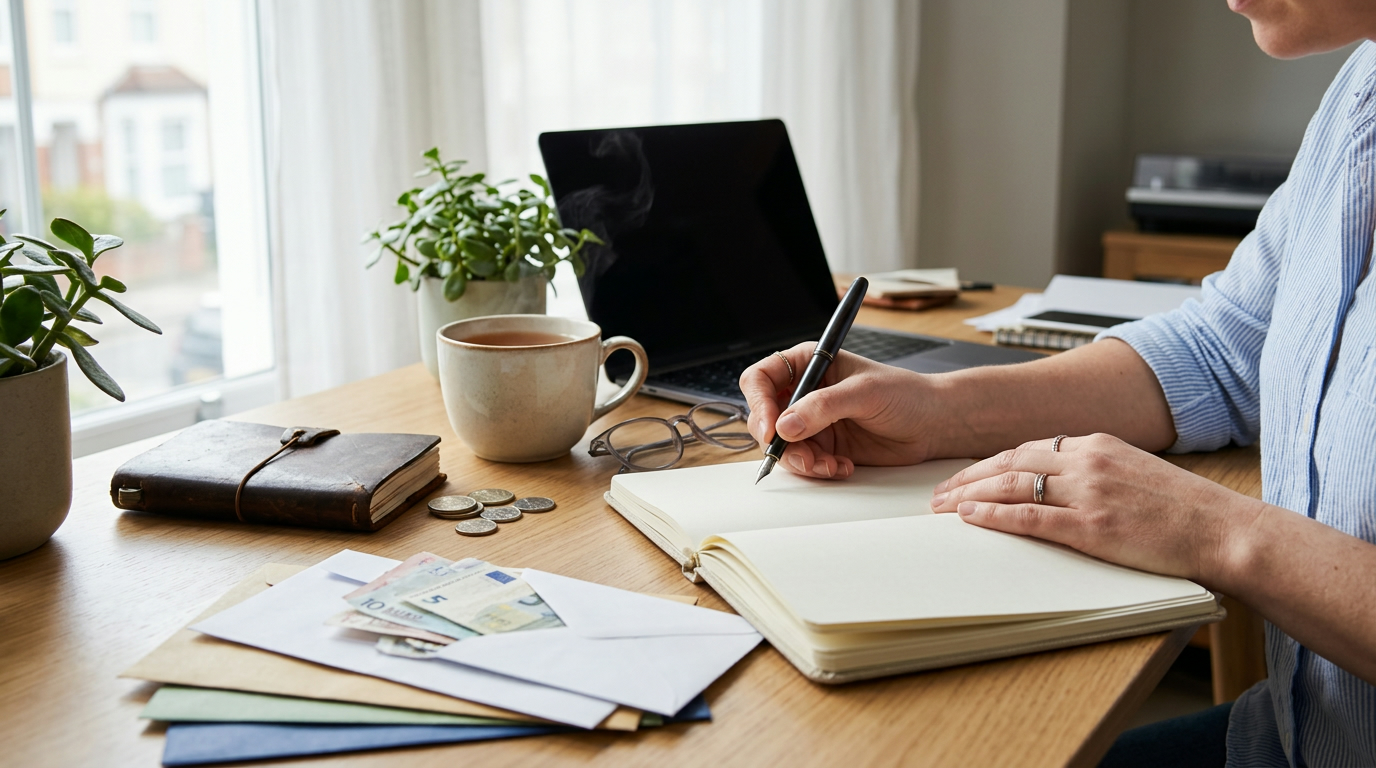
Even a small emergency fund can help you handle an unexpected expense without automatically adding to a credit-card balance, so choose an initial savings target you can reach and build from there. Keep that money accessible for genuine emergencies, while setting aside separate amounts for predictable but infrequent expenses so they do not repeatedly disrupt your plan.
For debt, write down each balance, interest rate, minimum payment, and due date, then make at least the minimum payments while directing any extra money toward a deliberate payoff strategy. Paying the highest-interest debt first generally reduces interest costs, while paying the smallest balance first may help you stay motivated; the better choice is one you can sustain without neglecting essentials.
Check the product’s listed specifications when evaluating build a cushion and make debt manageable.
Featured in this guide
The Money Confidence Power-Up for Women Checklist | Empowering Digital Download to Build Financial Clarity & Control | Boost Money Confidence for Women
Check your workplace benefits, insurance coverage, and beneficiaries so you understand what would happen if you became ill, could not work, or died, particularly if someone depends on your income. If you share finances with a partner, stay familiar with account access, recurring bills, debts, and important documents rather than leaving the day-to-day details to one person.
Retirement planning matters even when it feels distant: learn whether your employer offers a matching contribution, understand your investment choices and fees, and increase contributions when your budget allows. Women’s careers and earnings can be affected by caregiving or time away from paid work, so revisit your savings plan after those transitions instead of assuming an old contribution amount will remain sufficient.
You do not need to fix every part of your finances at once; pick one action for this week, such as reviewing a statement, setting up an automatic transfer, or finding out the interest rate on a debt. Then give yourself a date to revisit it, because financial confidence grows through repeated, informed decisions rather than a single perfect plan.
For a step-by-step starting point, read our guide to money confidence for women. Use what fits your circumstances, and consider speaking with a qualified financial professional when a decision involves complex taxes, investments, or legal obligations.
“This checklist is a lifesaver! It’s helped me gain so much clarity on my finances. 💪🏼”
Useful topics include budgeting, emergency savings, debt, credit, retirement, insurance, and knowing how to access your accounts and financial documents. Pay particular attention to how changes in pay, caregiving, or household responsibilities affect your own long-term security.

Leave a comment